Hot Chili tightens metrics on South American copper growth engine

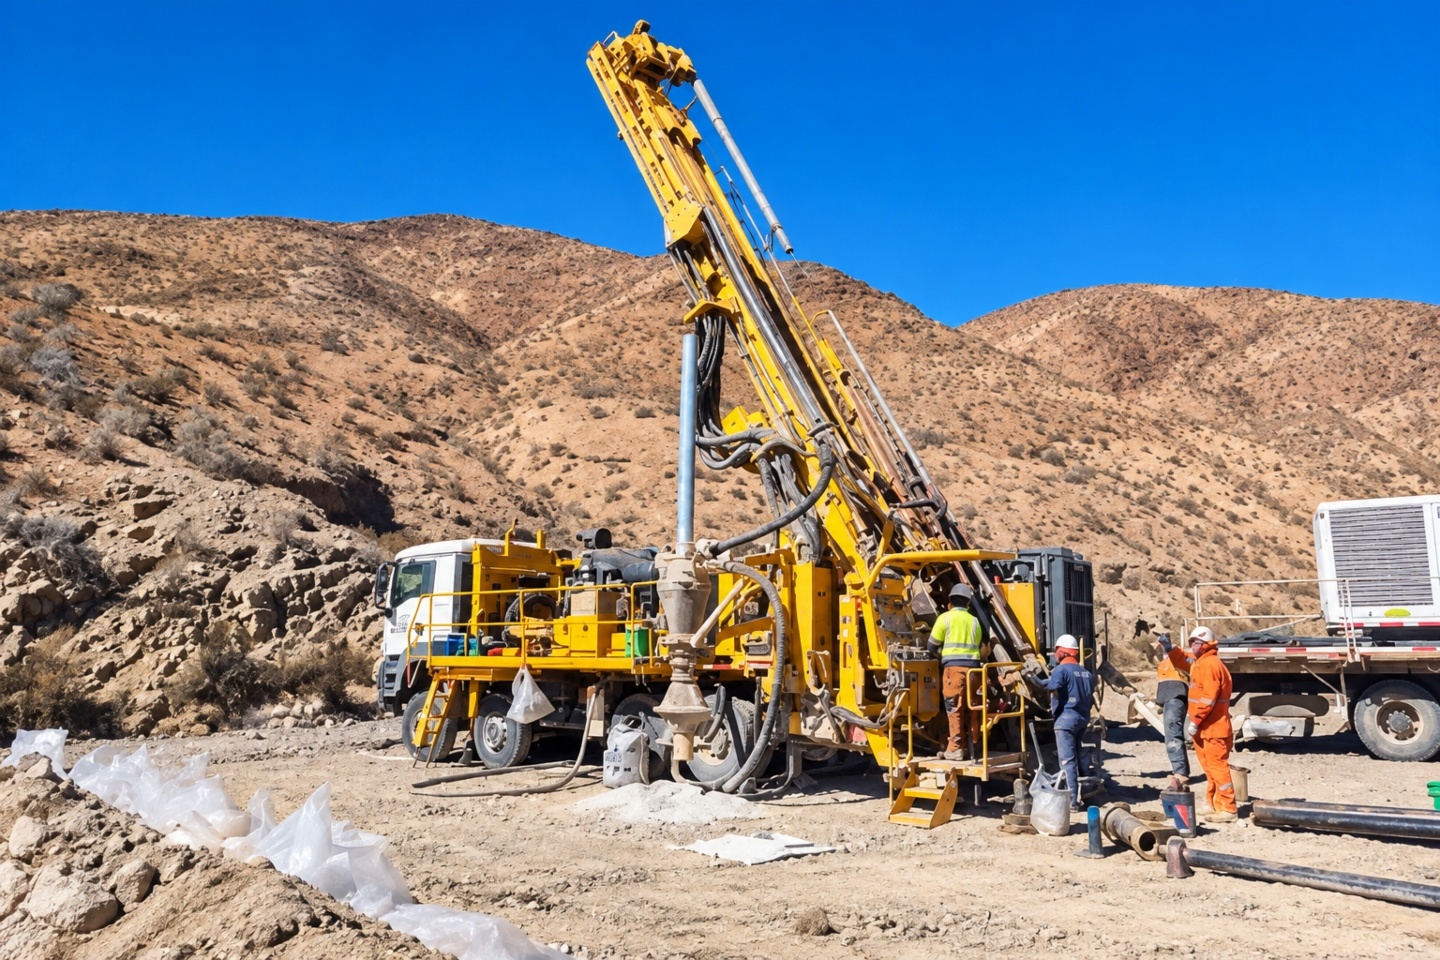
Hot Chili Limited (ASX: HCH) is furiously drilling out La Verde, a deposit management believes is shaping up as a company-making copper-gold discovery in Chile's coastal Atacama region. The emerging system sits 35km southeast of the planned Productora processing hub at the company's flagship Costa Fuego copper-gold development.
More than 33,000m of drilling has now outlined mineralisation across a 1000m by 800m footprint extending to 800m in depth and still open in all directions. Fourteen holes have delivered significant intersections above 0.7 per cent copper equivalent, a measure combining copper, gold, silver and molybdenum values into an equivalent copper grade.
The drill ledger carries some serious widths. Standouts include 725m at 0.42 per cent copper equivalent from 18m, including 62m at 1.03 per cent, and 472m at 0.41 per cent from 49m.
Another particularly telling hole delivered 398m at 0.45 per cent copper equivalent from surface, including 62m at 0.91 per cent from 20m. With mineralisation kicking off beneath only shallow gravel cover, the result adds further weight to La Verde’s emerging scale and development potential.
That opportunity comes sharply into focus when stacked against the size of the operation La Verde could ultimately feed. Costa Fuego has 798 million tonnes of measured and indicated material at 0.45 per cent copper equivalent alongside another 203Mt at 0.31 per cent in the inferred category. Its 502Mt probable reserve underpins a 2025 study that maps out annual production of 116,000 tonnes of copper equivalent across the first 14 years, generating a US$1.2B ($1.7B) post-tax net present value and 19 per cent internal rate of return.
With a central processing hub already planned at Productora, management believes La Verde's shallow, higher-grade material could strengthen the front end of Costa Fuego's mine schedule once incorporated into the study, with the 398-metre398-metre hole providing a strong pointer to what the near-surface opportunity could deliver.
The hole is among the strongest near-surface intersections we have drilled at La Verde so far, with comparable grades are now appearing across the deposit, we have confidence in the scale of a potential high-grade starter pit for Costa Fuego. Hot Chili Limited Managing Director Christian Easterday
The company now has two diamond rigs working double shifts and two reverse-circulation rigs on single shifts at La Verde, with southern step-out drilling underway. Shallow drilling is defining the near-surface enrichment zone, while deeper step-outs are testing the porphyry's higher-grade core and bulk-tonnage extensions.
Further results are expected as Hot Chili drives towards a first La Verde resource estimate this year. Those numbers will then be incorporated into a major Costa Fuego resource upgrade and an upscaled prefeasibility study.
Management says integrating La Verde could support a 20–30-year operation producing between 100,000 and150,000 tonnes per annum (tpa) copper equivalent. However, the company is keen to emphasise the range represents growth potential rather than the existing prefeasibility study production target, with no certainty at this stage it will be achieved. Environmental permit submission is slated for the second quarter of 2027, ahead of a 2029 final investment decision and first production in 2031.
Running alongside the mine plan is Hot Chili's 80 per cent-owned Huasco Water business, which holds what it describes as the Huasco Valley's only active maritime licence with permitted seawater access. The company plans to harness an initial 500 litres per second (L/s) of seawater for Costa Fuego. At the same time, it is advancing a second maritime concession, with potential desalinated-water expansion to 1300L/s and ultimately 2300L/s across the thirsty district.
Copper is supplying a roaring backdrop. The metal is trading today at US$14,528.75 ($20,340.25) per tonne, equivalent to US$6.59 ($9.23) per pound and well north of the US$4.30 ($6.02) per pound long-term assumption underpinning Costa Fuego's study. Hot Chili's study estimates every US$0.10 per pound increase above that assumption adds roughly US$100M to its post-tax net present value, adding huge potential economic weight.
With $46M in cash as of the end of the June quarter, Hot Chili has the firepower to keep testing just how much La Verde can add to the mix. The next resource and study work should put hard numbers around a discovery, fast-tracking the heart of the Costa Fuego story.
Is your ASX-listed company doing something interesting? Contact: office@bullsnbears.com.au


